Suez Is Back. What 30 Days by Sea Actually Measures
The Suez reopening is moving faster than most shipping plans assumed. Roughly 50% of canal capacity is back, the market expects about 80% by year-end, and ocean transit from Yantian to Rotterdam has fallen to about 27 days on the OA Alliance express service and about 30 days on Maersk’s Gemini service. Carriers have been blanking sailings and shifting capacity to the transpacific, so Europe-bound rates have not rallied as expected and hold around USD 3,000.
The obvious reading is that rail is under pressure again. The report itself says as much: ocean’s value proposition has clearly improved, particularly for general cargo that is not in a hurry, and rail platforms face a harder fourth quarter than they did a third.
That reading is fair. The comparison underneath it usually is not.
Two clocks that do not start in the same place
Thirty days by sea is a port-to-port figure: Yantian to Rotterdam. Twenty-one days by rail is a figure from a Chinese origin to a European station — Xi’an express to Duisburg, in the report’s table.
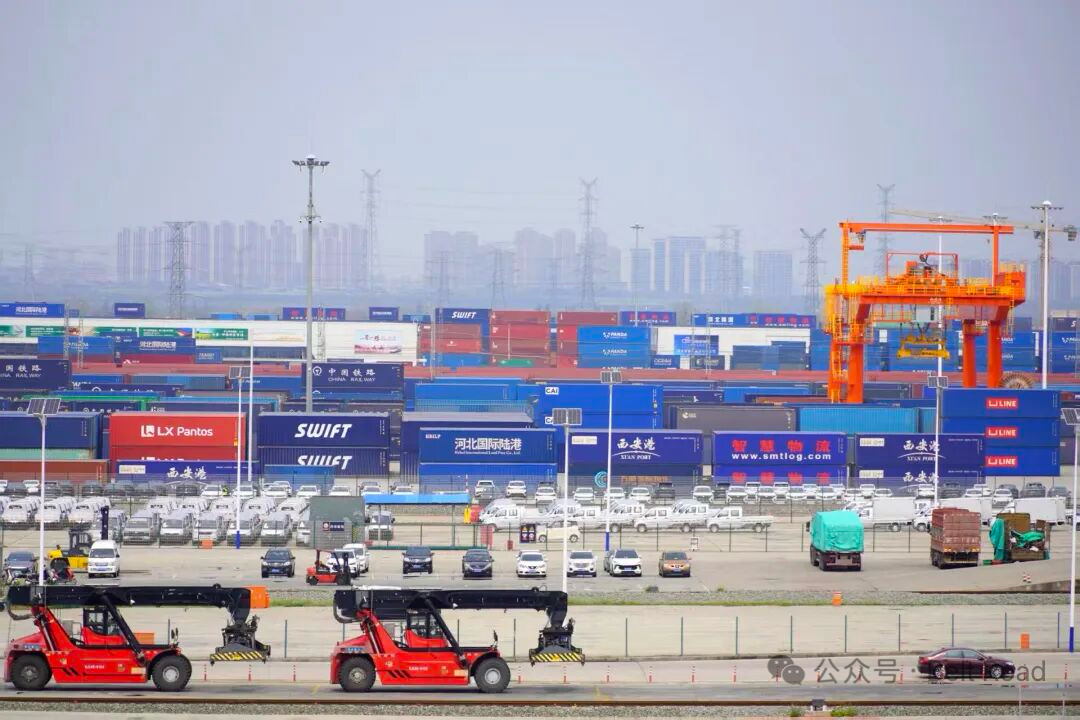
They differ at both ends. The ocean number begins at a coastal port, which means an inland factory first has to get its container to Yantian. The rail number begins at an inland origin such as Xi’an, Chongqing or Chengdu, where much of that inland haul is already part of the route. At the far end, Rotterdam is a port and Duisburg is a rail terminal; neither is a warehouse.
There is a wrinkle in the rail table worth reading closely. The report labels its figures “door-to-station average transit time”, then states in the note that they include border transshipment and the onward leg but exclude drayage and customs at both ends. Those two statements do not sit comfortably together. The sensible way to use the table is as a rail-leg reference, not as a door-to-door promise — and to ask who is pricing the legs it leaves out.
What the rail table actually shows
Here is a slice of the report’s transit reference for 30 October to 6 November:
| Origin | Destination | Average transit |
|---|---|---|
| Xi’an (express) | Hamburg | 21 days |
| Xi’an (express) | Duisburg | 21 days |
| Xi’an (regular) | Duisburg | 26 days |
| Chongqing (express) | Duisburg | 24 days |
| Chengdu | Hamburg | 28 days |
| Xi’an (express) | Milan | 28 days |
| Chengdu | Milan | 32 days |
| Xi’an (TE) | Milan | 34 days |
The widest gap is not between rail and sea. It is within rail, on Milan: about 28 days for Xi’an services that run express to Duisburg and then transship, against 32 to 34 days for regular services from Xi’an (TE), Chengdu and Jinhua. The report puts the gap down to border handling and onward connections. For a buyer, that is the useful finding — the routing decision can move a date more than the mode decision does.
One more line from the same period: express services from major origins ran 2-4 days longer week on week, with Hamburg-bound lanes generally slower. A transit reference is a snapshot, not a commitment.
The border is a second clock
The same report also publishes border-level handling times, as of 2 November: Alashankou–Dostyk at 5-7 days with 3,300+ containers waiting, Khorgos–Altynkol at 7-10 days with 4,800+, Manzhouli at up to 7 days for a block train but 14 or more for break-bulk, and Erenhot at 5-8 days or beyond 10 when wagons are short. Brest–Malaszewicze, on the European side, is the smoothest leg at 3-5 days.
These are a different measurement from the origin-to-destination table. They describe what happens at a border, not the whole journey, and the report says the backlog figures come from overseas agents and platform feedback and are indicative only. Do not add them to the 21 days and do not subtract them from the 30.
Our previous border-crossing update covered the same crossings a week earlier. The two reports do not use identical definitions — Erenhot, for one, is described differently in each — so we are not going to present a week-on-week change that the sources cannot support.
And a third clock, inside Germany
Transit tables assume the line stays open. In this period it did not, everywhere.
A hazardous materials leak at Krefeld suspended rail services and delayed all Neuss-bound trains, with Deutsche Bahn yet to confirm a restart date. Then, from 6 to 9 November, temporary infrastructure restrictions closed the Biederitz–Magdeburg Brücke section on the Guben–Neuss route entirely. Both landed inside the same reporting window.
That is the sort of thing no comparison table captures: a disruption a thousand kilometres from the border, on a leg the buyer never sees quoted separately.
Where the comparison actually lands
For cargo that is not time-sensitive, the report’s own conclusion stands — ocean looks better than it did, and you should price it. Where we would push back is on treating the two transit numbers as interchangeable inputs to the same decision.
Three questions settle it more reliably than a headline:
Where does each clock start? If your factory is inland, the rail figure already contains the haul that the ocean figure assumes you will arrange separately.
Where does each clock stop? A port and a rail terminal are both intermediate points. Ask for the inland leg and customs on each side before comparing dates.
What happens at a queue? A backlog at a border crossing is not a delay on a timetable; it is a variable in the release of your slot. When a crossing runs at 4,800+ waiting containers, the booking date is the number to pin down, not the advertised transit.
The ocean freight route and the rail route are both real options, and the honest answer changes with where the goods are made and where they are consumed. We would rather build the two legs into one comparison than argue about nine days that were never measured the same way.
Demand is softer on both sides
One background condition is worth keeping in view. By November, European receivers had largely finished Christmas and New Year stocking, and bulk and general cargo volumes were falling, leaving project cargo to carry most lanes. The report notes that thin demand is pressing on spot rates and making some platforms more cautious about releasing space.
That is a seasonal observation, not a forecast, and it cuts both ways: softer demand can mean more room to negotiate, and it can mean fewer departures to choose from.
Let’s talk before you switch modes
Send us your origin, destination and the date the cargo actually has to arrive. We will put the two quotes on the same footing — same start point, same end point, same inland legs — and tell you which one holds up once the border and the last mile are counted.
No commitment required. Just a conversation.
Email: [email protected]
WhatsApp: https://wa.me/message/QPR7JMHO3NFZE1
Based in: Xi’an International Trade & Logistics Park
Archer Sourcing helps European, Central Asian, and Middle Eastern businesses move cargo from China via the China-Europe Railway Express and overland corridors. We operate from Xi’an — the departure hub of the Chang’an rail service.